
 Download

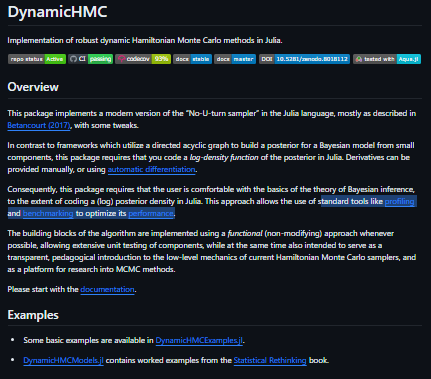
Implementation of robust dynamic Hamiltonian Monte Carlo methods in Julia. In contrast to frameworks that utilize a directed acyclic graph to build a posterior for a Bayesian model from small components, this package requires that you code a log-density function of the posterior in Julia. Derivatives can be provided manually, or using automatic differentiation. Consequently, this package requires that the user is comfortable with the basics of the theory of Bayesian inference, to the extent of coding a (log) posterior density in Julia. This approach allows the use of standard tools like profiling and benchmarking to optimize its performance.
Features
- The building blocks of the algorithm are implemented using a functional (non-modifying) approach whenever possible
- Examples available
- Derivatives can be provided manually, or using automatic differentiation
- Robust dynamic Hamiltonian Monte Carlo methods (NUTS) in Julia
- Modern version of the “No-U-turn sampler” in the Julia language
- Standard tools like profiling and benchmarking to optimize its performance
Project Samples
Categories
Data VisualizationLicense
MIT LicenseFollow DynamicHMC
Other Useful Business Software
$300 Free Credits to Build on Google Cloud
Put your $300 in credit toward real workloads, then keep building with free monthly usage for 20+ products. No commitment and no charge until you upgrade.
Rate This Project
Login To Rate This Project
User Reviews
Be the first to post a review of DynamicHMC!
